Quantum Hamiltonian Monte Carlo Sampling for Optimization
Abstract: Monte carlo sampling algorithms have seen a resurgence in interest as a technique to efficiently generate good candidate solutions to non-linear optimization problems.
The Hamiltonian Markov chain Monte Carlo (HMC) algorithm is a good fit for this task because it enjoys mixing rates that are by its design robust to factors that can confound other MCMC methods.
A key paradigm to view quantum computing for optimization also treats it as a sampler of good candidate solutions. Existing quantum methodology shows that classical Markov chain methods (on discrete state spaces) enjoy a speed up in their mixing times when quantized. We construct a quantization scheme for HMC that extends this result while preserving its classical robustness. We sketch early results on applying this technique to the convex body volume estimation problem.
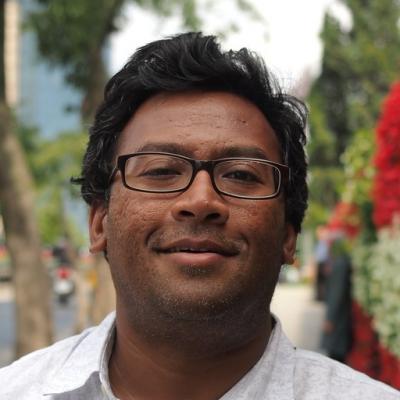
Bio: Soumyadip Ghosh is a member of IBM Research in the Algorithms and Applications group at Yorktown Heights. His research focuses on stochastic optimization and decision making under uncertainty, with a recent focus on constructing efficient hybrid quantum classical algorithms with applications to optimization formulations that arise in finance, insurance and healthcare. He has worked previously on smarter grid and energy analytics, cloud infrastructure, and supply chain management. He is an associate editor of Stochastic Models and has served as a committee member for INFORMS / WSC.